This WACC Calculator estimates your weighted average cost of capital: the required return on the debt and equity used to finance a business. It weights each funding source by its share of total capital and adjusts the cost of debt for the interest tax benefit.
Use the result to assess financing scenarios, evaluate investments with comparable risk, or estimate a discount rate for business valuation.
How to use the WACC calculator
Enter your financing amounts and annual rates in the five input fields:
| Input | What to enter |
|---|---|
| Total Debt | The value of interest-bearing financing, such as loans and bonds—not all balance-sheet liabilities. |
| Total Equity | The value of shareholders’ equity. For market-based WACC, use market value rather than accounting book value. |
| Cost of Debt | The annual borrowing cost before tax. If you have several loans, use a weighted average rate appropriate to your analysis. |
| Cost of Equity | The annual return shareholders require for bearing the investment’s risk—not the dividend yield or historical accounting return. |
| Tax Rate | The corporate tax rate applicable to the interest deduction. The formula assumes the resulting tax benefit can be used. |
Enter percentage rates as whole percentages: type 9 for 9%, not 0.09. Use the same currency and scale for debt and equity. For example, do not enter debt in dollars and equity in millions.
The calculator returns WACC as a percentage. Debt and equity must total more than zero; either source can be zero when modeling an all-equity or all-debt structure.
Choosing reliable inputs
For valuation, market-value or target capital weights are generally more appropriate than book values. For a private business, equity value may require a separate valuation estimate. Using book equity can produce a useful accounting-based scenario, but it is not equivalent to market-value WACC.
Use current financing conditions when estimating the cost of new capital. Historical loan rates may help describe existing financing, but they may not represent what lenders would charge today. Likewise, the calculator uses your cost-of-equity estimate; it does not calculate that estimate for you.
WACC formula
WACC = [E ÷ (E + D)] × Re + [D ÷ (E + D)] × Rd × (1 − T)
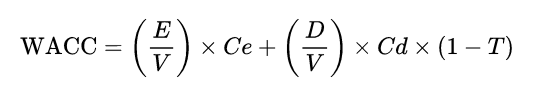
- E: equity value.
- D: debt value.
- E + D: total debt and equity capital.
- Re: cost of equity.
- Rd: pretax cost of debt.
- T: applicable corporate tax rate.
For a manual calculation, express rates as decimals and multiply the final result by 100 to display a percentage. The calculator handles these conversions when you enter percentage inputs.
The term Rd × (1 − T) is the after-tax cost of debt. Do not enter an already tax-adjusted borrowing rate in the Cost of Debt field, or the calculation will apply the tax benefit twice.
Worked WACC calculation
Suppose ACME has $5 million in equity and $2 million in debt. Shareholders require an 8% return, the pretax borrowing cost is 5%, and the applicable tax rate is 30%.
- Total capital: $5 million + $2 million = $7 million.
- Equity weight: 5 ÷ 7 = approximately 71.43%.
- Debt weight: 2 ÷ 7 = approximately 28.57%.
- After-tax debt cost: 5% × (1 − 0.30) = 3.5%.
WACC = (5 ÷ 7 × 0.08) + (2 ÷ 7 × 0.05 × 0.70) = 0.067142857, or approximately 6.71%.
This is an estimated required annual return on the business’s combined capital. It is not a cash interest bill: the equity component represents investors’ required return, even when the company pays no dividend.
Comparing equity financing with a new loan
Now suppose ACME needs another $3 million. The following scenarios show how changing the inputs affects WACC:
| Scenario | Equity | Debt | Cost of equity | Pretax cost of debt | WACC at 30% tax |
|---|---|---|---|---|---|
| Starting position | $5 million | $2 million | 8% | 5% | 6.71% |
| Raise $3 million in equity | $8 million | $2 million | 9% | 5% | 7.90% |
| Borrow $3 million at 6% | $5 million | $5 million | 8% | 5.6% | 5.96% |
The equity scenario assumes a revised required equity return of 9%; issuing shares does not automatically cause that increase. In the loan scenario, the blended debt cost is [($2 million × 5%) + ($3 million × 6%)] ÷ $5 million = 5.6%, not 6% on all debt.
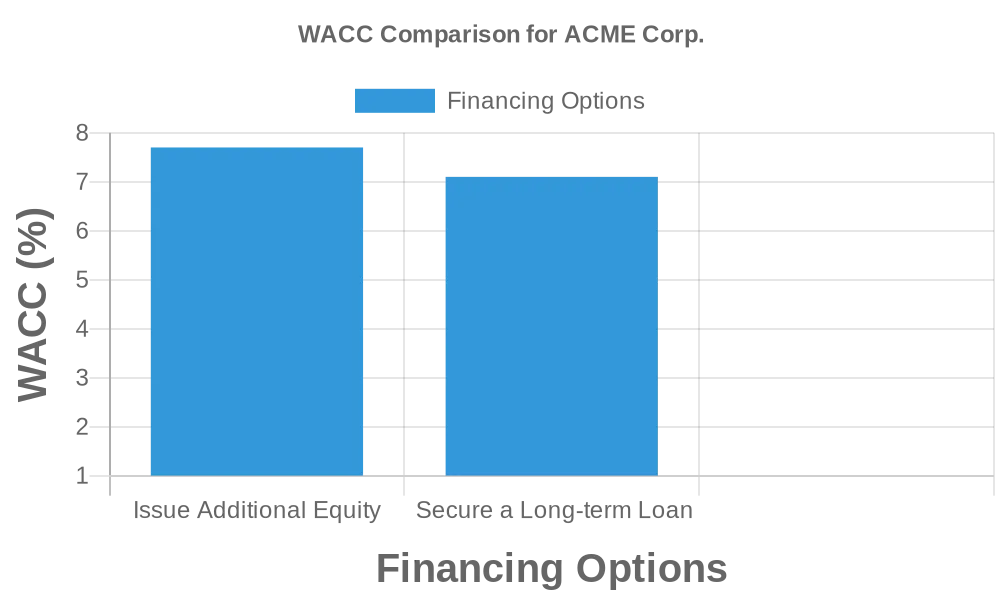
The loan scenario has the lower calculated WACC under these assumptions. However, it holds the cost of equity constant for illustration. Additional leverage can raise both shareholder risk and borrowing costs, so a lower modeled WACC alone does not establish the best financing choice.
What is a good WACC?
There is no universally good WACC. It depends on business risk, leverage, market conditions, currency, and the valuation date. A lower rate generally means capital providers require a lower return, but it does not prove that management is making better investment decisions.
A useful comparison is Return on Invested Capital (ROIC). When consistently measured after-tax ROIC exceeds WACC, it suggests the business is earning more than its estimated cost of capital. Check that the periods and capital definitions are comparable before drawing conclusions.
For external context, KPMG’s Cost of Capital Study and Professor Aswath Damodaran’s industry cost-of-capital data provide estimates to investigate. Check each dataset’s date, geography, currency, and methodology rather than treating an industry average as your company’s required rate.
Using WACC in investment decisions
- Business valuation: WACC can discount free cash flow to the firm—the cash flow available to both debt and equity providers. It is not generally the appropriate discount rate for cash flows available only to shareholders.
- Project evaluation: For a project with risk comparable to the business, WACC can serve as a starting discount rate. Positive net present value at an appropriate rate indicates estimated value creation under the forecast assumptions.
- Financing analysis: Compare alternative debt and equity mixes, updating the required returns as leverage changes rather than assuming rates stay fixed.
Match the rate to the cash flows: nominal rates with nominal forecasts, real rates with inflation-adjusted forecasts, and a consistent currency throughout. A riskier project or division may need a different discount rate from the company-wide WACC.
Advisory firms can use Calcopolis to build a customized ROI calculator that helps prospects compare projected investment returns with an assumed cost-of-capital hurdle rate before requesting a consultation.
Important limitations and related calculators
This calculation models two funding categories: debt and equity. It does not separately model preferred stock, changing capital structures over time, or limits on interest deductibility. If the business cannot use the assumed tax deduction, the formula may overstate the tax benefit and understate WACC.
Revisit your assumptions when interest rates, business risk, tax treatment, or financing plans change. Testing several plausible equity costs and capital structures is often more informative than relying on one precise-looking percentage.
- ROCE measures operating profitability relative to capital employed. Because it commonly uses pretax operating profit, it is not directly comparable with after-tax WACC without adjustments. The ROCE Calculator can help examine that complementary measure.
- The Unlevered Beta Calculator helps separate operating risk from leverage effects when developing risk assumptions for the cost of equity.
- The Tax Shield Calculator helps estimate tax savings from deductible expenses, providing context for the tax adjustment applied to debt costs.