This internal rate of return calculator helps you evaluate an investment using its initial cost and subsequent cash flows. IRR is the discount rate that makes the net present value (NPV) of those cash flows equal to zero. It expresses a return rate per cash-flow period—not a total profit percentage or a guaranteed future return.
How to use the IRR calculator
Prepare your cash flows in chronological order, starting with the investment made today. Standard IRR calculations assume equal intervals between cash flows, such as months or years.
- Start with the initial investment. Represent money paid out as a negative cash flow. For example, a $1,000 investment is −1,000.
- Add subsequent net cash flows in order. Money received is positive; additional spending is negative. If you receive $600 and pay $100 in expenses during a period, its net cash flow is $500.
- Keep the spacing consistent. Do not mix monthly and annual periods. Include a zero for any period with no cash flow rather than skipping it.
- Include the investment's ending value when appropriate. Add expected net sale proceeds or a remaining asset value to the final period's cash flow. Do not count the same proceeds twice.
- Interpret the rate using the same time unit. Annual cash flows produce an annual IRR; monthly cash flows produce a monthly IRR.
Use one currency throughout and include at least one negative and one positive cash flow. These opposite signs are necessary for a standard IRR calculation, but they do not guarantee that a unique, usable result exists.
If your cash flows occur on irregular dates, use the date-based alternative discussed below rather than treating uneven intervals as equal periods.
How to calculate IRR: the formula
NPV discounts each future cash flow back to its present value, then adds those values to the initial cash flow:
NPV(r) = CF0 + CF1 / (1 + r) + CF2 / (1 + r)2 + … + CFn / (1 + r)n
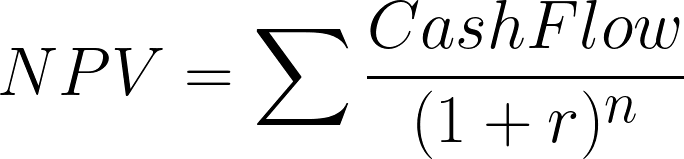
- CF0: the initial cash flow at time zero, usually a negative investment.
- CFt: the net cash flow at the end of period t.
- r: the discount rate per period, expressed as a decimal in the formula.
- n: the number of periods after the initial investment.
The IRR formula uses the same cash flows but solves for the rate that makes NPV zero:
0 = CF0 + CF1 / (1 + IRR) + … + CFn / (1 + IRR)n
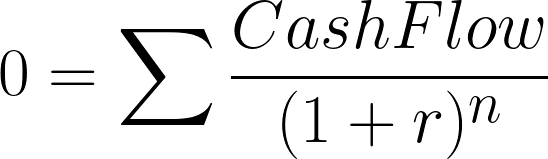
For most multi-period investments, finding that rate requires numerical methods: testing and refining a rate until NPV is sufficiently close to zero. IRR is a discounted break-even rate; it does not mean that the investment produces no cash profit.
Worked example: a $1,000 investment
Suppose you invest $1,000 today and receive payments at the end of each of the next three years:
| Time | Net cash flow |
|---|---|
| Today, year 0 | −$1,000 |
| End of year 1 | $500 |
| End of year 2 | $400 |
| End of year 3 | $300 |
The equation is:
0 = −1,000 + 500 / (1 + r) + 400 / (1 + r)2 + 300 / (1 + r)3
The annual IRR is approximately 10.65%. Discounting the three payments at that rate gives a combined present value of approximately $1,000, offsetting the initial investment.
The undiscounted profit is $200, or 20% of the initial investment over the full three years. That is not a 20% annual return: IRR accounts for when each payment arrives.
What does your IRR result mean?
Compare IRR with your required rate of return, also called a hurdle rate. That benchmark should reflect the investment's risk and your opportunity cost. For a business project, an appropriate cost of capital may help establish it.
For a conventional investment—an initial outflow followed only by inflows—the usual interpretation is:
| Comparison | Interpretation |
|---|---|
| IRR exceeds the required return | NPV is positive at that required return; the projected cash flows clear the hurdle. |
| IRR equals the required return | NPV is zero; the investment just meets the hurdle. |
| IRR is below the required return | NPV is negative at that required return; the investment falls short. |
In the example above, a 10% required annual return gives an NPV of approximately $10.52. The investment therefore clears that hurdle, but only narrowly. If your required return were 12%, it would not.
There is no universal “good IRR.” A higher projected rate does not automatically compensate for greater risk, uncertain forecasts, limited liquidity, or a longer holding period.
Is IRR always an annual rate?
No. The rate follows the cash-flow interval. To convert a monthly IRR to an effective annual rate, use (1 + monthly IRR)12 − 1, with the monthly rate expressed as a decimal. For example, a 1% monthly IRR is approximately 12.68% annually—not 12%.
Common IRR mistakes and limitations
- Choosing the highest percentage without considering scale. A small project can have a higher IRR while creating less dollar value than a larger project. Compare NPV at an appropriate discount rate, especially when you can select only one project.
- Overlooking multiple or missing solutions. Cash flows that switch signs more than once—for example, an initial investment, income, and a final cleanup cost—can produce multiple IRRs or no usable IRR. A single reported rate may not tell the full story.
- Treating forecasts as certain. IRR summarizes the cash flows you supply; it does not measure their likelihood. Test lower receipts, higher costs, delayed payments, and a lower sale price.
- Mixing inconsistent assumptions. Compare after-tax cash flows with an after-tax required return, and nominal cash flows with a nominal required return. Keep financing assumptions consistent with whether you are evaluating the whole project or the owner's equity.
- Assuming reinvestment at the IRR. The calculated rate does not guarantee that interim distributions can earn the same return elsewhere. Modified IRR (MIRR) can help when you want explicit financing and reinvestment assumptions.
Using IRR in investment decisions
Use IRR to compare cash-flow scenarios, then check the dollar impact and the assumptions driving the result.
- Rental property: include acquisition costs, net rental income, major repairs, and final sale proceeds after selling costs. If evaluating your equity return, also account consistently for borrowing and debt payments.
- Equipment purchases: compare the upfront purchase and installation costs with incremental operating savings, maintenance costs, and expected resale value.
- Business expansion: include startup spending, working capital, and incremental operating cash flows—not accounting revenue or profit alone.
For each scenario, change one important assumption at a time. If a modest cost increase pushes IRR below your hurdle rate, investigate that cost before relying on the investment case.
IRR, XIRR, ROI, and CAGR: which should you use?
- XIRR calculator: use actual cash-flow dates when contributions and withdrawals are irregularly spaced. XIRR produces an annualized rate based on those dates.
- Return on Investment (ROI): use it for a simple total return relative to investment cost. Unlike IRR, a basic ROI calculation does not account for payment timing.
- Compound Annual Growth Rate (CAGR): use it to measure annualized growth between a starting and ending value when there are no intermediate external cash flows. CAGR smooths the growth rate; it does not measure volatility.
Use NPV alongside IRR when you need to estimate how much value an investment adds in today's money at your chosen required return.
Build an investment calculator for your website
If your business presents property investments, equipment savings, or project proposals, Calcopolis lets you build a customized investment return calculator around your assumptions. Help visitors estimate potential returns and submit a more informed inquiry.