Use this compound interest calculator to estimate how a starting balance could grow over time when interest stays invested. Enter your initial amount, annual interest rate, investment period, compounding frequency, and tax rate to explore a savings or investment scenario.
What is compound interest?
Compound interest is interest earned on both your original deposit and previously accumulated interest. Unlike simple interest, which is calculated only on the original principal, compounding allows the amount earning interest to increase over time.
For example, $1,000 earning 5% annually earns $50 in the first year. If that interest stays invested, the next year's interest is calculated on $1,050, producing $52.50.
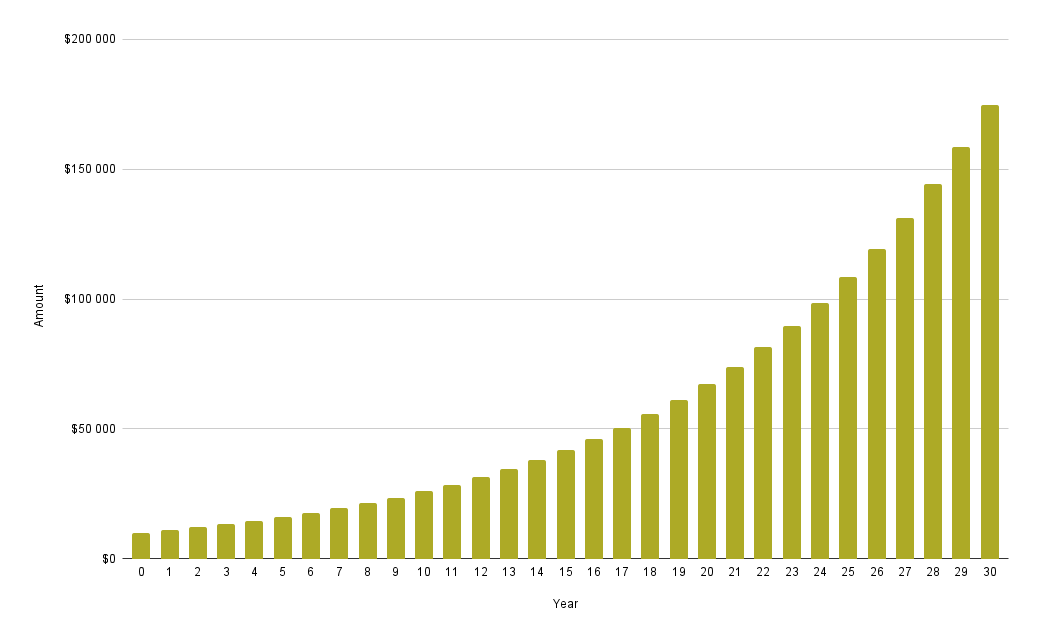
The following chart illustrates long-term growth from a $1,000 starting balance at an assumed 10% annual rate. It is an illustration, not a promised investment return.
How to use the compound interest calculator
- Initial amount: Enter the money invested at the start. This calculator models a starting balance, not a series of additional deposits.
- Interest rate: Enter the annual rate as a percentage: enter 5 for 5%, not 0.05. For the standard formula below, this is the nominal annual rate before compounding.
- Time period: Enter how long the money will remain invested, checking the displayed time unit. The formula below expresses time in years.
- Compounding: Choose monthly, quarterly, or annually to match the account's terms. These correspond to 12, 4, or 1 compounding periods per year.
- Tax rate: Enter the tax percentage applicable to your interest income. Use 0% when exploring growth before tax or a scenario where no tax applies.
Although the amount field displays a dollar sign, the mathematics is currency-independent. You can interpret the amounts as euros, Ghanaian cedis, or another currency, provided you use the same currency throughout. The calculator does not perform currency conversion.
If you plan to contribute regularly, use the savings calculator instead. The timing and size of additional deposits affect the result.
The compound interest formula
The standard formula for a single starting deposit, before taxes and fees, is:
A = P × (1 + r/n)n × Y
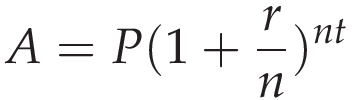
- A is the future balance, including the initial deposit and accumulated interest.
- P is the principal, or initial amount.
- r is the nominal annual interest rate expressed as a decimal: 5% becomes 0.05.
- n is the number of compounding periods per year.
- Y is the investment period in years. The formula image uses t for this same time variable; it is not the calculator's Tax rate field.
To find the interest earned rather than the total balance, subtract the initial amount:
Interest earned = A − P
The formula assumes a constant rate, reinvested interest, and no deposits or withdrawals during the period. Actual accounts may also apply daily accrual rules, rounding, fees, or restrictions on when interest is credited.
How compounding frequency affects growth
Compounding frequency describes how often earned interest is added to the balance that earns future interest. At the same positive nominal annual rate, more frequent compounding produces a higher final balance.
For example, $10,000 at a 5% nominal annual rate grows to $10,500 after one year with annual compounding, or approximately $10,511.62 with monthly compounding, before tax and fees.
The effective annual interest rate includes this compounding effect:
Effective annual rate = (1 + r/n)n − 1
At 5% nominal interest compounded monthly, the effective annual rate is approximately 5.116%. If an account advertises an APY or effective annual yield, do not treat it as a nominal rate and compound it again; that would overstate growth.
Can I calculate weekly compound interest?
This calculator offers monthly, quarterly, and annual compounding, but not weekly compounding. For a standard weekly compound interest calculation, use n = 52 in the formula above. Choosing monthly compounding does not reproduce a weekly schedule.
Worked example and compound interest schedule
Suppose you invest $10,000 at 5% annually for three years, with annual compounding and a 0% tax rate. There are no additional deposits or withdrawals.
A = $10,000 × (1 + 0.05/1)1 × 3 = $11,576.25
Your final balance is $11,576.25, of which $1,576.25 is interest. The schedule below shows how each year's interest becomes part of the next year's starting balance.
| Year | Starting balance | Interest earned | Ending balance |
|---|---|---|---|
| 1 | $10,000.00 | $500.00 | $10,500.00 |
| 2 | $10,500.00 | $525.00 | $11,025.00 |
| 3 | $11,025.00 | $551.25 | $11,576.25 |
With simple interest, the same starting amount and rate would earn $500 each year, giving a $11,500 balance after three years. Compounding adds $76.25 in this example.
What happens over a longer period?
For a longer illustration, $100,000 at a constant 10% nominal annual rate, compounded monthly for 30 years, grows to approximately $1,983,739.94 before tax and fees. No additional contributions are included.
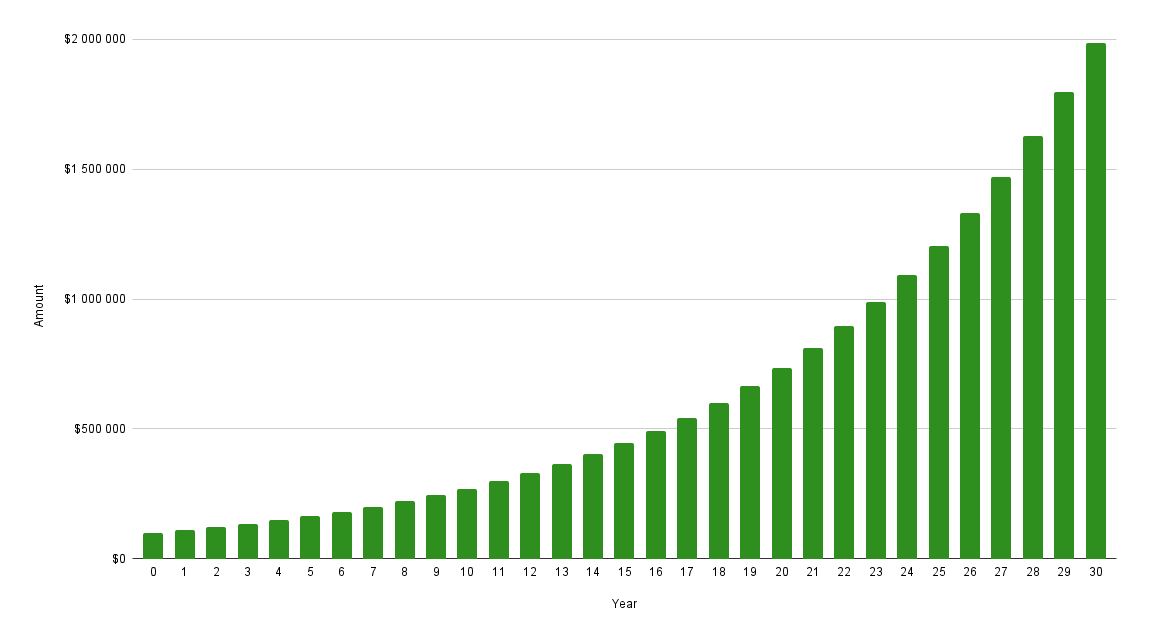
The curve becomes steeper because the same percentage return applies to a larger balance. This mathematical pattern depends on a sustained positive rate; it does not mean that a real investment will deliver steadily increasing returns.
How to interpret and apply your result
- Separate your capital from your earnings. A final balance includes your original deposit. Subtract that deposit to understand how much growth the scenario produces.
- Check tax timing. Tax deducted whenever interest is credited leaves less money available to compound than tax paid at the end. A tax percentage alone does not describe this timing, so check the account's tax rules before treating an after-tax estimate as an exact payout.
- Account for purchasing power. A larger nominal balance may buy less than expected after inflation. Use the inflation calculator to examine purchasing-power changes; inflation is not simply a negative interest rate applied to your account balance.
- Include costs in your decision. Account fees, investment expenses, and withdrawal penalties can reduce what you keep. There is no separate fee input in this calculator.
- Test more than one rate. Compare lower, middle, and higher assumptions, especially for investments without a guaranteed return. Change one input at a time to see its effect clearly.
When is a compound growth estimate useful?
Savings accounts and certificates of deposit: Use the account's stated rate and compounding terms to estimate growth from a lump sum. For variable-rate accounts, the result assumes the entered rate remains unchanged.
Stocks, funds, and portfolios: The formula can model a hypothetical constant compound return, including reinvested income. It does not predict market performance. Returns fluctuate, losses are possible, and a simple arithmetic average of annual returns may overstate compound growth.
Comparing savings decisions: Test whether leaving money invested longer or choosing a different rate meaningfully changes your projected balance. Consider access to your money, risk, and account terms alongside the numerical result.
Related savings planning tools
- For a target amount, use the savings goal calculator. Your savings rate helps you assess how much of your income you are setting aside.
- To explore withdrawals rather than accumulation, try the living off savings calculator.
- To place your savings within your wider financial position, calculate your net worth, including assets and liabilities.
For savings providers and financial educators, a calculator tailored to specific products can make rates and term options easier to understand. Use Calcopolis's savings calculator builder to create a website calculator with relevant assumptions and a path to an inquiry.