The Future Value Calculator estimates how much a lump sum could grow to over time at a constant interest rate. Enter your starting balance, annual rate, investment duration, and compounding frequency to calculate its projected future value.
This calculator models a single starting amount. It does not include regular contributions or withdrawals, so use it to estimate the growth of money you already have invested.
How to use the future value calculator
- Present Value: Enter your initial investment or current savings balance in dollars.
- Interest Rate: Enter the annual interest rate as a percentage. For example, enter 5 for 5%, not 0.05.
- Time period: Enter how long the money will remain invested. For a 10-year projection, use a duration of 10 years.
- Compounding: Select monthly, quarterly, or annually to match how often interest is added to the balance.
The Future Value result is the projected ending balance, including your starting amount and accumulated interest. Compounding means that interest added to the balance can earn interest in later periods.
For future value with contributions, use the Future Value of Annuity Calculator to model regular payments, or the Regular Saving Calculator to explore ongoing savings.
What is future value?
Future value is the estimated value of money at a specified future date, assuming a particular rate of return. It answers a practical question: “If I invest this amount now and leave it untouched, how much could it be worth later?”
This is an application of the time value of money: money available today has earning potential. Future value projects a current amount forward; present value works backward from a future amount.
The future value formula
For annual compounding, the formula is:
FV = PV × (1 + r)t
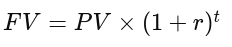
To account for more than one compounding period per year, use:
FV = PV × (1 + r/n)nt
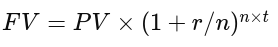
- FV: Future value, or the projected ending balance.
- PV: Present value, or the starting balance.
- r: Annual interest rate expressed as a decimal. A 5% rate becomes 0.05.
- n: Compounding periods per year: 1 for annually, 4 for quarterly, or 12 for monthly.
- t: Investment duration in years. For a duration expressed in months, divide the number of months by 12.
The calculator converts your percentage input to a decimal and divides it by the number of compounding periods per year. The exponent is the total number of compounding periods over the investment duration.
How compounding frequency changes the formula
At the same positive nominal annual rate, more frequent compounding produces a higher future value. The difference depends on the rate and duration; it is not a substitute for comparing fees, risk, and other account terms.
-
Annually: Interest compounds once per year, so n = 1.
-
Semiannually: Interest compounds twice per year, so n = 2. This formula is included for reference; semiannual compounding is not an option in this calculator.
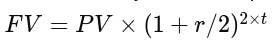
-
Quarterly: Interest compounds four times per year, so n = 4.
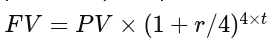
-
Monthly: Interest compounds 12 times per year, so n = 12.
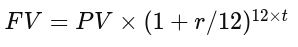
For example, $1,000 earning a nominal annual rate of 5% grows to $1,050.00 after one year with annual compounding, compared with approximately $1,051.16 with monthly compounding.
Worked example: $10,000 invested for 10 years
Suppose you invest $10,000 at 5% annual interest, compounded annually, and make no additional deposits or withdrawals.
| Calculator field | Value to enter |
|---|---|
| Present Value | $10,000 |
| Interest Rate | 5% |
| Time period | 10 years |
| Compounding | Annually |
FV = $10,000 × (1 + 0.05)10 = $16,288.95
The projected ending balance is $16,288.95. To calculate interest earned, subtract your initial investment:
Interest earned = $16,288.95 − $10,000 = $6,288.95
The future value is therefore the total balance, not just the investment gain. Both figures are before any taxes or fees not reflected in the rate.
How to interpret your result
Treat the result as a projection under your chosen assumptions, not a guaranteed payout. Check these points before using it in a financial plan:
- Nominal rate versus APY: With monthly or quarterly compounding, the formula treats your input as a nominal annual rate. APY already includes the effect of compounding, so entering an APY with those settings would overstate growth. For a constant APY projection, use that rate with annual compounding.
- Constant growth: The calculation assumes the same rate throughout the period. Market investments do not generally earn a smooth, fixed return, and losses are possible.
- No cash flows: Deposits and withdrawals change the outcome. Compounding frequency describes how often interest is added, not how often you contribute.
- Taxes and fees: These are not calculated separately. Account charges and investment taxes can reduce the amount you keep, and their effect depends on when and how they apply.
- Inflation: The result is a future dollar amount, not its purchasing power in today's dollars.
To express the result in today's purchasing power, use inflation-adjusted value = FV ÷ (1 + f)t, where f is the assumed annual inflation rate as a decimal and t is the number of years. Simply subtracting inflation from the nominal return is only an approximation.
Use the calculation to test a savings goal
For a home down payment, education fund, or retirement balance, compare the projected future value of your existing savings with the amount you expect to need at the target date. A gap shows how much of the goal your current balance would not cover under those assumptions.
Change one input at a time to understand what drives the result:
- Starting balance: At the same rate and duration, doubling the initial investment doubles its future value.
- Time: Test whether a later target date provides enough additional growth. Money needed soon may require a different approach from long-term savings.
- Rate: Compare several plausible return scenarios rather than relying on one optimistic estimate. A higher assumed return does not make that return achievable or account for additional risk.
If your plan depends on monthly deposits, switch to a contribution-based calculator rather than adding all future deposits to the starting balance. That shortcut incorrectly assumes every deposit earns interest for the entire period.
Related financial planning calculators
- Present Value Calculator: Work backward to estimate the amount needed today to reach a future sum at a chosen discount rate.
- Compound Interest Calculator: Explore how reinvested interest affects savings growth.
- Present Value of Annuity Calculator: Find the present value of a series of future payments rather than one future lump sum.
- FIRE Calculator: Explore a broader financial independence and early retirement goal.
Offer a savings projection on your website
Financial educators and savings providers can use Calcopolis to build a customized savings calculator, helping visitors explore projections using assumptions relevant to their services before making an inquiry.