The present value calculator estimates what a single future payment is worth today, based on an interest rate, a time period, and a compounding frequency. Use it to compare a future payout with cash available now or estimate the lump sum needed today to reach a future savings target.
How to use the present value calculator
- Future Value: Enter the amount you expect to receive or need at the future date. This is one lump sum, not a recurring payment.
- Interest Rate: Enter the annual rate as a percentage—for example, enter 5 for 5%. This rate acts as the discount rate used to translate future money into today's value.
- Time period: Enter how long it will be before the payment occurs. Check the time unit carefully: six months and six years produce very different results.
- Compounding: Select monthly, quarterly, or annually to match the rate convention you are using.
- Present Value: Read the calculated current value of the future amount, expressed in dollars.
The result assumes a constant rate throughout the selected period. The calculator does not separately account for taxes, fees, inflation, or the possibility that a promised payment will not arrive.
What does present value mean?
Present value, or PV, expresses a future amount of money as an equivalent amount today at a chosen discount rate. It reflects the time value of money: money available now can earn a return before a future payment arrives.
For example, at a positive discount rate, a guaranteed $1,000 received six years from now is worth less than $1,000 received today. Present value measures that difference under your chosen assumptions; it does not determine a universally correct price.
The present value formula
To account for the calculator's compounding options, the present value formula is:
PV = FV / (1 + r/c)c × t
- PV: Present value in dollars.
- FV: Future value in dollars.
- r: Annual interest or discount rate as a decimal. Divide the percentage entered in the calculator by 100.
- c: Compounding periods per year: 1 annually, 4 quarterly, or 12 monthly.
- t: Time in years. If a duration is expressed in months, its year equivalent is the number of months divided by 12.
More generally, if r represents the rate per period and n is the total number of periods, the formula becomes PV = FV / (1 + r)n.
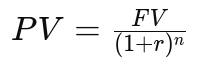
Worked example: $1,000 received in six years
Suppose you expect to receive $1,000 in six years and use a 5% annual discount rate with annual compounding:
PV = $1,000 / (1 + 0.05)6 = $746.22
Under these assumptions, $746.22 today is approximately equivalent to $1,000 in six years. In reverse, investing that amount at 5% compounded annually would grow to approximately $1,000, before taxes and fees.
How compounding affects present value
The selected frequency determines both the rate per period and the number of periods. At the same positive nominal annual rate, more frequent compounding produces a slightly lower present value. It is a different rate convention, not automatically a more accurate estimate.
Annual compounding
The annual rate is applied once per year. For the example above, the result is $746.22.
Quarterly compounding
Divide the annual rate by four and multiply the years by four. A $1,000 payment in six years discounted at a nominal annual rate of 5% has a present value of $742.20.
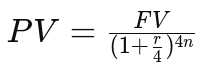
Monthly compounding
Divide the annual rate by 12 and multiply the years by 12. The same payment discounted at a nominal annual rate of 5% has a present value of $741.28.
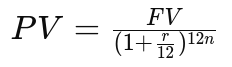
Semiannual compounding: a related formula
Semiannual compounding divides the annual rate by two and doubles the number of years. The formula is included for reference, but semiannual compounding is not an option in this calculator.
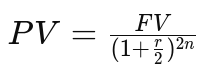
Choosing a discount rate and interpreting the result
The rate should reflect the comparison you are making. For a savings target, it might be an assumed investment return. When evaluating a future payment, it might be your required return or the return available from an alternative with comparable risk and timing.
- A higher discount rate lowers present value for a positive future amount and a positive time period.
- A longer wait lowers present value when the discount rate is positive.
- At a 0% rate, present value equals future value. There is no discounting.
Check whether your quoted rate is nominal or effective. The monthly and quarterly settings divide the entered annual rate across those periods. If you start with an effective annual yield, such as APY, select annual compounding and enter that effective annual rate rather than treating it as a nominal rate.
Present value is not automatically inflation-adjusted purchasing power
Discounting at an investment return is different from adjusting for inflation. Keep your assumptions consistent: use nominal future amounts with a nominal discount rate, or inflation-adjusted amounts with a compatible real rate. Do not subtract inflation twice.
A discounted estimate also does not guarantee payment. For an uncertain bonus, investment payout, or business receivable, consider payment risk separately. Testing several reasonable discount rates can show how sensitive your estimate is to the rate assumption.
Practical ways to use your result
- Compare cash now with a future payout. In the worked example, $800 today exceeds the $746.22 present value of $1,000 in six years at 5% annually. That comparison holds only under the stated assumptions.
- Estimate a one-time investment for a future goal. Enter the amount you expect to need and an assumed return. The result estimates the initial deposit required, without additional contributions.
- Evaluate a single-payment investment. Compare its purchase price with the present value of its expected payout. A price below PV indicates a positive discounted surplus at your chosen rate, not proof that the investment is safe.
This calculator discounts one future amount. For multiple payments on different dates, discount each payment separately and add the present values. Recurring deposits, bond coupons, loan installments, and changing rates require additional calculations.
Related calculators for your next step
- Present Value of Annuity Calculator: Find today's value of a series of equal, regularly spaced payments rather than one lump sum.
- Compound Interest Calculator: Explore the opposite direction—how money invested today can grow over time.
- Future Value of Annuity Calculator: Estimate the accumulated future value of regular payments.
For broader investment comparisons, the Return on Investment Calculator measures gain relative to cost, while the Internal Rate of Return Calculator estimates the discount rate at which a project's net present value equals zero. For mortgage payment estimates rather than a single discounted amount, use the Mortgage Calculator.
Build a calculator for your financial website
If your business explains lump-sum payouts or savings goals, Calcopolis's WordPress calculator builder lets you create a customized calculator with assumptions and explanations tailored to your audience, helping visitors estimate values before requesting a consultation.