The Marginal Revenue Calculator measures the additional revenue earned per extra unit sold. Enter either the changes in revenue and quantity or the totals for two periods to calculate marginal revenue in dollars per unit.
Marginal revenue measures revenue, not profit. To decide whether additional sales are worthwhile, compare the result with the additional costs required to generate them.
How to use the marginal revenue calculator
Select a Method based on the information you have:
- Change in revenue and quantity: Enter the change in total revenue in dollars and the change in quantity in units. Use the differences between your two sales levels, not the ending totals.
- Compare two periods: Enter Revenue and Quantity for Period 1, then Revenue and Quantity for Period 2. The calculator subtracts Period 1 from Period 2 before dividing the revenue change by the quantity change.
For either method, use revenue and units sold for the same product or consistent product group. Compare periods of equal length, and use the same treatment of discounts, returns, and other revenue adjustments.
The change in quantity must not be zero. If quantity is unchanged, marginal revenue is undefined because the calculation would divide by zero. Although the result field displays dollars, interpret the answer as dollars per additional unit.
Marginal revenue formula
The calculator uses the following formula:
Marginal revenue = Change in total revenue ÷ Change in quantity sold
MR = (TR2 − TR1) ÷ (Q2 − Q1)
- TR1 and TR2: total revenue at the initial and later sales levels.
- Q1 and Q2: units sold at those same sales levels.
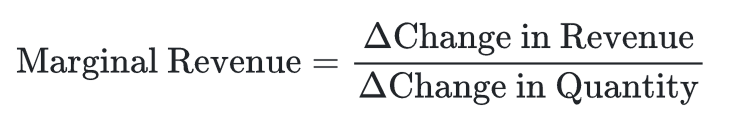
If quantity increases by exactly one unit, the result is the revenue gained from that unit. If it increases by several units, the result is the average incremental revenue per unit over that interval. It does not show how marginal revenue varies within the interval.
Worked example: evaluating additional sales
Suppose ABC Electronics currently sells 10,000 phones per month and earns $2,000,000 in revenue. It estimates that selling 11,000 phones would generate $2,150,000. These are hypothetical sales projections, not a forecast produced by the calculator.
Using Compare two periods, enter:
| Input | Period 1 | Period 2 |
|---|---|---|
| Revenue | $2,000,000 | $2,150,000 |
| Quantity | 10,000 units | 11,000 units |
The calculation is:
- Change in revenue = $2,150,000 − $2,000,000 = $150,000.
- Change in quantity = 11,000 − 10,000 = 1,000 units.
- Marginal revenue = $150,000 ÷ 1,000 = $150 per unit.
You would get the same result by selecting Change in revenue and quantity and entering $150,000 and 1,000 units.
Does $150 per unit mean the expansion is profitable?
Not by itself. Suppose the additional 1,000 phones cost $100 each to produce and sell, with no other incremental costs. Additional costs would be $100,000, so the projected increase in profit would be $150,000 − $100,000 = $50,000.
New equipment, overtime, shipping, returns, or extra marketing could reduce that gain. Include all costs caused by the expansion before making a decision.
How to interpret your result
When quantity sold increases:
- Positive marginal revenue: total revenue rises. A higher value means more revenue gained per additional unit, but not necessarily more profit.
- Zero marginal revenue: additional units produce no net increase in total revenue.
- Negative marginal revenue: total revenue falls despite selling more units. For example, a price reduction across all sales may outweigh revenue from the extra units.
If quantity falls, interpret the signs carefully. A $1,000 revenue decline divided by a 100-unit decline gives positive $10 per unit. That describes revenue lost per unit of reduced sales—not revenue growth.
Why marginal revenue differs from selling price
Selling price applies to a unit sold; marginal revenue measures the change in total revenue. They can differ when selling more requires reducing prices on units you would otherwise have sold at a higher price.
In the electronics example, average revenue per phone falls from $200 to about $195.45, while marginal revenue is $150. The revenue increase accounts for the overall change in sales, not just the price charged for the additional phones.
For a price-taking seller receiving the same fixed price for every unit, marginal revenue equals that price. Do not assume this relationship holds when discounts or pricing changes affect existing sales.
Using marginal revenue in business decisions
- Evaluate promotions: compare total revenue before and after a discount, including its effect on existing sales—not just the extra units sold.
- Assess expansion: compare incremental revenue and incremental costs over the same quantity interval. Producing more only creates sales revenue if those units sell.
- Test smaller sales increments: a profitable 1,000-unit expansion does not establish that the next 1,000 units will be profitable. Recalculate using updated demand, pricing, and cost estimates.
A two-period comparison measures an observed revenue change; it does not prove that selling more caused the entire change. Seasonality, product mix, price changes, and customer behavior can affect the result. This calculator also does not estimate demand or identify a profit-maximizing quantity on its own.
Related calculators for a fuller analysis
- Marginal Cost Calculator: calculate the additional cost per unit and compare it with marginal revenue over the same interval.
- Profit Calculator: assess revenue after costs rather than treating revenue growth as profit growth.
- Break-even analysis: estimate the sales volume needed to cover fixed and variable costs under your pricing assumptions.
If customers need to explore quantity-based prices on your website, use Calcopolis to build a customized pricing calculator that reflects your volume discounts and helps visitors estimate an order before requesting a quote.