The average variable cost calculator finds the variable cost of producing one unit of a product or delivering one unit of service. Divide your total variable costs by the corresponding output to see how much each unit costs before fixed expenses.
Important: the calculator’s “Total Costs” field should contain only variable costs. If you include fixed costs, the result will be average total cost rather than average variable cost.
How to use the average variable cost calculator
- Enter your variable costs in “Total Costs.” Add the costs that change with production or service volume, using dollars consistently.
- Enter output in “Total Quanity.” Use the number of units associated with those costs. The field is labeled in pieces; for a service business, use a consistent service unit, such as completed appointments.
- Read “Average Variable Cost.” Although the result displays a dollar unit, interpret it as dollars per unit of output.
Use costs and output from the same period, product, and production scope. For example, divide the variable costs of producing a monthly batch by the units produced in that batch—not by units sold from a different batch.
Quantity must be greater than zero because average variable cost is undefined at zero output. Entering zero variable costs with positive output gives an AVC of $0 per unit; check that no relevant costs have been omitted.
Average variable cost formula
The average variable cost formula is:
AVC = TVC ÷ Q
- AVC: average variable cost, measured in dollars per unit.
- TVC: total variable cost for the selected output.
- Q: quantity produced or service units delivered.
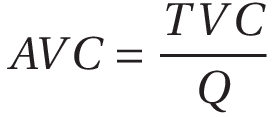
The calculator divides the amount entered in “Total Costs” by “Total Quanity.” It does not separate fixed and variable expenses for you.
Worked example: $100,000 of variable costs
Suppose a manufacturer produces 2,000 units in one month and records these variable expenses:
| Variable expense | Monthly cost |
|---|---|
| Raw materials | $60,000 |
| Piece-rate production labor | $20,000 |
| Packaging | $12,000 |
| Production-related energy usage | $8,000 |
| Total variable costs | $100,000 |
AVC = $100,000 ÷ 2,000 = $50 per unit.
This means each unit carries an average of $50 in variable expenses. It does not mean the business’s full cost is $50 per unit: rent, fixed salaries, and other fixed expenses still need to be covered.
Which expenses count as variable costs?
Variable costs change as activity changes. Classification depends on how the expense behaves in your business, not just its accounting label.
- Materials and packaging: inputs consumed for each unit produced.
- Production labor: piece-rate pay or other labor costs that change with output.
- Energy: the portion of electricity or fuel usage attributable to production volume.
- Sales and fulfillment costs: commissions, transaction fees, and per-order shipping when they are included in the scope of your analysis.
Some expenses are mixed. An electricity bill may include a fixed connection charge plus usage charges. Include only the variable portion when calculating AVC.
Keep your cost scope consistent. A production-only AVC and an AVC that also includes selling and fulfillment expenses answer different questions. Do not compare them as though they measure the same thing.
If you already know total cost and total fixed cost for the same output, you can calculate TVC = total cost − total fixed cost before entering the variable amount.
How to interpret your AVC result
A lower AVC means fewer variable-cost dollars per unit for the output being measured. It may reflect lower input prices, reduced waste, or more efficient labor. A higher AVC may reflect supplier increases, overtime, smaller batches, or a more expensive product mix.
There is no universal “good” AVC. Compare your result with your selling price, previous periods, budget, and comparable products using the same cost definitions.
Average variable cost is not marginal cost
AVC describes the average variable expense across all units in the calculation. Marginal cost measures the change in total cost caused by producing additional units. Use the marginal cost calculator when you need to evaluate the cost of extra output rather than the average cost of existing output.
Multiplying current AVC by additional units is only a reasonable estimate when variable cost per unit is expected to remain stable. Supplier discounts, overtime premiums, waste, or capacity constraints can change that relationship.
More output does not automatically lower AVC
Producing more units spreads fixed expenses over more output, reducing average fixed cost. It does not automatically reduce average variable cost. AVC falls only if variable spending per unit falls—for example, through a lower material price or less scrap.
The AFC calculator measures fixed cost per unit. For the same output and cost scope, average total cost = average variable cost + average fixed cost.
Use AVC for pricing and break-even planning
Compare AVC with the selling price to estimate what each unit contributes toward fixed costs and profit. For this purpose, make sure your variable cost figure includes all relevant variable selling and fulfillment expenses, not just manufacturing costs.
Contribution per unit = selling price per unit − variable cost per unit
Using the $50 AVC example, a $75 selling price leaves $25 per unit to cover fixed expenses. If monthly fixed costs are $30,000, the break-even point is:
Break-even units = $30,000 ÷ ($75 − $50) = 1,200 units.
This assumes a constant selling price, a stable $50 variable cost per unit, unchanged fixed costs, and that units produced are sold. Each sale first covers its variable cost; the remaining contribution accumulates toward fixed costs and then profit.
If the price equals AVC, sales leave nothing toward fixed costs. If the price is below AVC, sales do not cover the included variable expenses. AVC alone, however, is not enough to decide whether to accept a special order or change production: consider incremental costs, available capacity, and any costs that can actually be avoided.
Check these figures before setting discounts with the markdown calculator. A discount reduces contribution unless offset by cost savings or other benefits.
Do not confuse contribution with gross profit. You can calculate gross margins using revenue and cost of goods sold, but cost of goods sold may include fixed production overhead. For a wider view of profitability, assess accounting profit; the economic profit calculator also considers opportunity costs.
Practical ways to monitor and reduce variable cost per unit
- Track components separately. Divide materials, variable labor, packaging, and other variable expenses by output to identify what caused an AVC change.
- Measure waste and rework. Material losses or repeated work can raise cost per finished unit even when supplier prices remain unchanged.
- Evaluate purchasing discounts carefully. Compare savings with extra storage, financing, and spoilage costs rather than assuming a larger order is cheaper overall.
- Compare similar products or services. An overall average can hide costly product lines or unusually complex jobs.
- Test production scenarios. Estimate both variable spending and output for each scenario, then enter each pair separately. The calculator divides your inputs; it does not forecast how costs will behave.
Review AVC when input prices, labor arrangements, production methods, or product mix change. Investigate the cause before changing prices or cutting spending, since a lower AVC is not an improvement if it results in unacceptable quality or service.
Build a calculator around your business’s pricing model
If customers need estimates based on quantities, materials, or service options, a customized calculator can turn those choices into a more useful quote. Calcopolis offers a pricing calculator builder for business websites for creating a calculator tailored to your own inputs and pricing rules, rather than relying on a single average cost for every order.