This contribution margin calculator shows how much sales revenue remains after variable costs, how large that amount is as a percentage of revenue, and how much profit remains after fixed costs.
The calculator’s “Contribution margin” result is the total for all units entered, not the contribution margin per unit. To find the per-unit amount, subtract variable cost per unit from selling price per unit.
How to use the contribution margin calculator
- Enter the selling price in dollars per unit. Use the price you expect to receive after discounts. Do not enter total sales revenue in this field.
- Enter variable cost in dollars per unit. Include costs that change with sales or production volume, such as materials, packaging, sales commissions, and transaction fees. If you know total variable costs, the average variable cost calculator can help convert them to a per-unit amount.
- Enter the number of units sold or expected to sell. Use a quantity that matches the period or scenario you are analyzing.
- Enter total fixed costs for that same period. These are costs that remain unchanged within the activity range being considered, such as rent or salaried administrative staff. Enter the total, not fixed cost per unit. The average fixed cost calculator is useful for analyzing how those costs are spread across units.
For example, use monthly sales volume with monthly fixed costs—not monthly volume with annual rent. Keep all monetary inputs in the same currency and separate fixed and variable portions of mixed costs where practical.
Use a positive selling price and a positive quantity to obtain a meaningful contribution margin ratio. If total revenue is zero, the ratio is undefined because its formula divides by revenue.
Contribution margin formulas
Let p be selling price per unit, c be variable cost per unit, q be the number of units, and f be total fixed costs. Sales revenue is p × q, and total variable cost is c × q.
| Metric | Formula | What it measures |
|---|---|---|
| Contribution margin per unit | p − c | Dollars available from each unit to cover fixed costs and profit |
| Total contribution margin | (p × q) − (c × q) | Dollars available from all units; this is the calculator’s contribution margin result |
| Contribution margin ratio | [(p × q) − (c × q)] ÷ (p × q) × 100% | Percentage of sales revenue remaining after variable costs |
| Generated profit | (p × q) − (c × q) − f | Amount remaining after the entered variable and fixed costs |
How the contribution margin ratio works
The contribution margin ratio formula divides total contribution margin by sales revenue and expresses the result as a percentage.
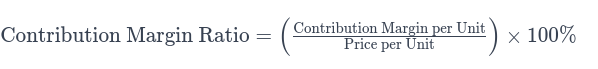
For one product with a constant selling price and variable cost per unit, the formula also simplifies to:
Contribution margin ratio = (Selling price − Variable cost per unit) ÷ Selling price × 100%
Quantity cancels out of this ratio. Increasing sales volume therefore increases total contribution margin, but it does not change the ratio unless selling price or variable cost per unit also changes.
Worked example: from unit contribution to profit
Suppose you sell a product for $100 per unit, incur $40 in variable cost per unit, sell 500 units, and have $20,000 in fixed costs for the period.
| Calculation | Result |
|---|---|
| Sales revenue: $100 × 500 | $50,000 |
| Total variable cost: $40 × 500 | $20,000 |
| Contribution margin per unit: $100 − $40 | $60 per unit |
| Total contribution margin: $50,000 − $20,000 | $30,000 |
| Contribution margin ratio: $30,000 ÷ $50,000 × 100% | 60% |
| Generated profit: $30,000 − $20,000 | $10,000 |
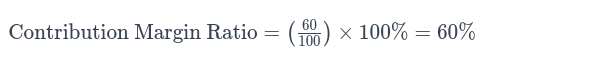
The 60% ratio means that 60 cents of every sales dollar remains after variable costs. That amount first covers fixed costs; only the remainder is profit. In this example, the calculator’s contribution margin result is $30,000, while the per-unit contribution is $60.
How to interpret your results
- Positive contribution margin: Sales provide money toward fixed costs. This does not guarantee a profit; total contribution must exceed fixed costs.
- Zero contribution margin: Selling price exactly covers variable cost. Sales provide nothing toward fixed costs.
- Negative contribution margin: Variable cost exceeds selling price. Selling more units increases the modeled loss if price and unit cost remain unchanged.
- Positive generated profit: Revenue covers the variable and fixed costs you entered.
- Negative generated profit: Total contribution is insufficient to cover the entered fixed costs.
A higher contribution margin ratio means more of each revenue dollar remains after variable costs. However, there is no universal “good” ratio: profitability also depends on sales volume, fixed costs, demand, and operating capacity.
Generated profit is a simplified estimate, not necessarily accounting net income. It includes only the costs represented in your inputs. Interest, taxes, depreciation, or other expenses affect the result only if you have included them appropriately.
Using contribution margin to find break-even sales
When contribution margin per unit is positive, you can estimate the sales volume needed to cover fixed costs:
Break-even units = Fixed costs ÷ Contribution margin per unit
In the example, $20,000 ÷ $60 = 333.33 units. If you sell whole units, you need at least 334 units to cover costs. At that volume, modeled profit is $40. The break-even point calculator can help you explore this threshold.
If unit contribution is zero or negative, increasing volume alone cannot cover positive fixed costs under the same assumptions.
How to apply contribution margin analysis
Check whether a discount can pay for itself
Using the same example, reducing the price from $100 to $90 while keeping variable cost at $40 lowers contribution per unit from $60 to $50. At 500 units, total contribution falls to $25,000 and generated profit falls to $5,000.
To preserve the original $30,000 total contribution, you would need to sell 600 units at the discounted price—a 20% increase in volume. This comparison assumes fixed costs and variable cost per unit do not increase at the higher volume.
Evaluate cost savings and product mix
Reducing variable cost by $2 per unit increases total contribution by $1,000 at 500 units. If fixed costs are unchanged, generated profit also increases by $1,000.
When comparing products, consider both contribution per unit and contribution ratio. If production time or another resource is limited, contribution per hour or per unit of that scarce resource may be more useful than either metric alone. Do not discontinue a product solely because its ratio is lower; also consider demand, avoidable costs, and its effect on other sales.
Contribution margin vs. gross margin
Contribution margin subtracts variable costs from revenue. Gross profit subtracts cost of goods sold; gross margin expresses that amount as a percentage of revenue.
These measures classify costs differently. Cost of goods sold may include fixed production overhead, while contribution margin may deduct variable selling costs that are excluded from cost of goods sold. Gross margin therefore does not simply subtract every fixed and variable business expense.
Use contribution margin for cost-volume-profit analysis and short-term scenario comparisons. Use a margin calculator when you need to express the difference between a selling price and a specified cost as a percentage of that price, checking which costs you include.
Build a pricing calculator for your business
If your team regularly compares prices, order quantities, and costs, a customized calculator can make those assumptions easier to review consistently. With Calcopolis’s pricing calculator builder, you can create a calculator for your business website—for example, a pricing tool that compares expected contribution across order sizes using your own cost rules.