The marginal cost calculator measures how much your total cost changes for each additional unit produced. Enter either the changes in cost and quantity directly or the totals for two periods to calculate the incremental cost per unit.
When you compare a batch of additional units, the result is the average additional cost across that batch—not necessarily the exact cost of producing the very next unit.
How to use the marginal cost calculator
Choose a Method based on the information you have:
-
Change in total cost and quantity:
- Enter Change in costs: the additional total cost of the production increase, in dollars.
- Enter Change in quantity: the number of additional units produced, not the final total output.
-
Compare two periods:
- Under Period 1, enter the starting total Costs and Quantity.
- Under Period 2, enter the new total Costs and Quantity.
The result labeled Marginal Cost is a dollar amount per unit. For example, a result of $50 means each additional unit costs $50 on average over the production change you entered.
Use comparable cost totals and the same unit of output throughout. When comparing periods, match their duration and cost categories; comparing one week with one month can produce a misleading result.
Marginal cost formula
Marginal cost = Change in total cost ÷ Change in quantity
Using starting and ending totals, the same formula is:
MC = (C2 − C1) ÷ (Q2 − Q1)
- C1 and C2 are total costs before and after the change.
- Q1 and Q2 are quantities produced before and after the change.
- MC is marginal cost, expressed in dollars per unit.
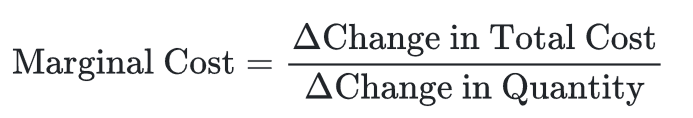
If output increases by exactly one unit, the result is the cost of that additional unit. For a larger increase, the calculator measures the average incremental cost over the selected range.
Worked example: a $5,000 cost increase
Suppose production rises from 1,000 to 1,100 units, while total costs rise from $20,000 to $25,000.
| Measure | Period 1 | Period 2 | Change |
|---|---|---|---|
| Total cost | $20,000 | $25,000 | $5,000 |
| Quantity produced | 1,000 units | 1,100 units | 100 units |
Marginal cost = ($25,000 − $20,000) ÷ (1,100 − 1,000) = $50 per unit.
You get the same result by selecting “Change in total cost and quantity” and entering $5,000 and 100 units. Do not divide $25,000 by 1,100 for this calculation—that would give the average total cost of all units, rather than the cost of the additional output.
Which costs should you include?
Use total costs measured consistently at both production levels. The subtraction then captures the costs that change with output, such as additional materials, labor, energy, packaging, and production-related fees.
Unchanged fixed costs cancel out. For example, if rent is $3,000 at both production levels, it contributes nothing to the cost increase. However, if expansion requires an extra production space or a new equipment lease, that additional cost belongs in the comparison.
Marginal cost differs from both average variable cost, which divides total variable costs by total output, and average fixed cost, which spreads fixed costs across all units. A new batch can cost more or less per unit than the units you already produce.
How to interpret your result
- A higher marginal cost means the additional output is more expensive per unit over the range being compared. Overtime, material shortages, or capacity limits may explain the increase.
- A lower marginal cost means the additional output is less expensive per unit. Better equipment utilization or supplier discounts may contribute.
- A zero result means total cost did not change despite a change in output. Check whether all additional costs were captured.
- A negative result during expansion means total cost fell while output increased. Verify the inputs and investigate discounts, efficiency improvements, or unrelated cost changes before treating this as a sustainable saving.
The change in quantity must not be zero. If both periods have the same output, the formula divides by zero and marginal cost cannot be determined from those figures.
Using marginal cost to evaluate additional production
Compare the additional cost with the additional revenue from the same production increase. The marginal revenue calculator helps express that revenue change per unit.
If additional revenue exceeds all relevant additional costs, the expansion improves profit under those assumptions. Selling price alone is an adequate revenue comparison only when the extra units sell at that price without reducing revenue from existing sales. Consider demand, discounts, delivery costs, and any alternative use of limited production capacity.
Example: electronics manufacturer
An electronics manufacturer plans to increase monthly production from 15,000 to 18,000 units. Total costs are expected to rise from $750,000 to $840,000.
Marginal cost = ($840,000 − $750,000) ÷ (18,000 − 15,000) = $30 per unit.
If all 3,000 additional units sell for $55 each, additional revenue is $165,000. Subtracting the $90,000 cost increase gives a $75,000 increase in profit, provided the cost estimate includes every relevant additional expense and existing sales are unaffected.
Example: local bakery
A bakery considers increasing monthly production from 2,000 to 2,500 loaves. Total costs would rise from $10,000 to $13,000.
Marginal cost = ($13,000 − $10,000) ÷ (2,500 − 2,000) = $6 per loaf.
At a selling price of $5 per additional loaf, the extra 500 loaves generate $2,500 in revenue but add $3,000 in costs. The expansion would reduce profit by $500 under these assumptions. The bakery could test a smaller batch, a higher price, or a lower-cost production schedule before proceeding.
What this calculation cannot tell you
A two-period comparison measures the cost difference; it does not establish why costs changed. Higher material prices, a different product mix, or a one-time repair can affect the result even when they are not caused by higher output.
The result also applies only to the range analyzed. Producing another 100 units after reaching capacity may cost much more than the previous 100. Compare smaller production increments when overtime, equipment purchases, or other capacity thresholds matter.
Finally, profitable additional production does not necessarily mean the entire business is profitable. Use break-even analysis to assess the sales volume needed to cover total fixed and variable costs.
Build a calculator for customer pricing estimates
If customers need estimates based on order quantity, materials, or setup charges, use Calcopolis to build a customized pricing calculator for your website. It can help visitors explore order sizes and provide clearer requirements when requesting a quote.