The Cost of Equity Calculator estimates the annual return shareholders require for investing in a company. Choose the Capital Asset Pricing Model (CAPM) to estimate that return from market risk, or the Dividend Capitalization Model to estimate it from dividends, share price, and dividend growth.
Cost of equity is a required return, not a guaranteed investment return or a cash payment the company must make. It represents shareholders’ opportunity cost: the return they could seek from another investment with comparable risk.
How to use the cost of equity calculator
Select a Method to display its inputs. Enter percentage rates as whole percentage values: enter 4 for 4%, not 0.04. Use annual rates and annual dividend figures if you want an annual cost of equity.
- Choose CAPM when you have a suitable risk-free rate, an expected broad market return, and an equity beta. The company does not need to pay dividends.
- Choose Dividend Capitalization Model when the company pays dividends and a stable, long-term dividend growth assumption is reasonable.
Replace any prefilled values with assumptions appropriate to the company and valuation date. The two methods can produce different estimates because they rely on different assumptions.
Cost of equity formula using CAPM
The Capital Asset Pricing Model (CAPM) adds compensation for market-related risk to a risk-free return:
Cost of equity (%) = f + β × (r − f)
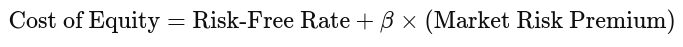
Here, f is the risk-free return rate, r is the expected broad market return rate, and β is the stock’s equity beta. Both return rates are entered as percentage values; beta is a unitless number.
What to enter for CAPM
- Risk-free return rate: Enter an appropriate government bond yield or other risk-free proxy. Match its currency and maturity as closely as practical to the cash flows you are evaluating.
- Broad market return rate: Enter the expected total annual return of the relevant equity market. Enter the full market return, not the market risk premium; the calculator subtracts the risk-free rate itself.
- Beta: Enter the company’s equity beta relative to the relevant market. Beta measures sensitivity to market movements, not all of the stock’s risk.
A beta of 1 indicates market-level sensitivity. A beta above 1 indicates greater sensitivity, while a positive beta below 1 indicates lower sensitivity. Beta estimates depend on the benchmark, measurement period, and the company’s financial leverage.
CAPM worked example
Suppose you enter a risk-free return of 4%, a broad market return of 7.8%, and a beta of 1.2:
- Market risk premium = 7.8% − 4% = 3.8 percentage points.
- Beta-adjusted premium = 1.2 × 3.8 = 4.56 percentage points.
- Cost of equity = 4% + 4.56% = 8.56%.
This estimates an annual required return of 8.56% under the selected assumptions. It does not predict that the stock will earn 8.56% over the next year.
Cost of equity formula using dividend capitalization
The Dividend Capitalization Model, based on the constant-growth dividend discount model, estimates the required return as the expected dividend yield plus dividend growth:
Cost of equity (%) = (D1 ÷ P0) × 100 + g
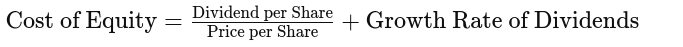
D1 is the expected dividend per share over the next year, P0 is the current share price, and g is the expected annual dividend growth rate entered as a percentage.
What to enter for dividend capitalization
- Dividend per share: Enter the expected total dividend per share for the next year. For example, four expected quarterly payments of $0.375 total $1.50 annually.
- Current market value: Enter the current price of one share, not the company’s total market capitalization. The numerator and denominator must both be on a per-share basis.
- Growth rate of dividend: Enter a sustainable annual dividend growth assumption, rather than assuming a recent unusually high growth rate will continue indefinitely.
The calculator uses the dividend amount you enter directly; it does not increase it by the growth rate first. If you only have the most recent annual dividend, estimate next year’s dividend separately as D1 = D0 × (1 + g ÷ 100).
Use the same currency for the dividend and share price, and use a positive share price.
Dividend capitalization worked example
For an expected annual dividend of $1.50 per share, a current share price of $25, and dividend growth of 3%:
Cost of equity = ($1.50 ÷ $25) × 100 + 3 = 6 + 3 = 9%
The 9% result combines a 6% expected dividend yield with 3% assumed dividend growth. This model is most useful for companies with predictable dividends; it is generally unsuitable for non-dividend-paying companies or businesses with highly irregular payouts.
How to interpret your cost of equity result
A higher cost of equity means shareholders require more compensation under your assumptions. Holding future equity cash flows constant, a higher required return produces a lower present value. A lower cost of equity produces a higher present value.
Neither result, by itself, establishes whether a stock is attractive. A high required return does not automatically make an investment undesirable, and a low required return does not mean a stock is undervalued or safe.
- Check sensitivity: In the CAPM example, increasing beta from 1.2 to 1.5 raises the result from 8.56% to 9.7%, with the other inputs unchanged. Test plausible assumptions rather than relying on one estimate.
- Keep assumptions consistent: Use a common currency and valuation date. Historical market returns can inform expectations, but they are not guaranteed future returns.
- Investigate differences between methods: A large gap may reflect an unsuitable beta, optimistic dividend growth, or an unusual payout policy. Do not automatically average the results.
- Recognize model limits: CAPM focuses on systematic market risk. The dividend model assumes stable growth indefinitely. Neither captures every company-specific risk.
Using cost of equity in valuation and investment decisions
The discount rate should match the cash flows being valued. Use cost of equity for cash flows available to equity holders. For cash flows available to both debt and equity providers, a suitable weighted average cost of capital (WACC) is generally the relevant rate.
- Equity valuation: Discount forecast cash flows to equity at a risk-appropriate cost of equity. Test how changes in the required return affect the estimated share value.
- Investment screening: Compare an expected equity return with the required return for comparable risk. An Internal Rate of Return (IRR) Calculator can help evaluate an equity cash-flow forecast, but the cash-flow basis and risk must match before comparing rates.
- Financial analysis: Distinguish required return from reported performance. Return on equity (ROE) measures accounting profit relative to book equity, while earnings per share (EPS) measures profit per share. Neither is the same as investors’ required market return.
Related calculators for capital-cost analysis
- Weighted Average Cost of Capital Calculator: Combine the cost of equity with the cost of debt and capital-structure weights.
- Capital Asset Pricing Model Calculator: Explore the relationship between the risk-free rate, market return, beta, and required return.
- Unlevered Beta Calculator: Separate the effect of financial leverage from equity beta. An unlevered beta generally needs to be relevered for the target capital structure before use in an equity CAPM estimate.
- Debt-to-Equity Ratio Calculator: Examine leverage when reviewing financing assumptions and differences in equity risk.
Build a calculator for your financial website
Financial advisory firms can use Calcopolis to build a customized investment return calculator that lets visitors explore assumptions and submit an inquiry with their inputs, giving advisors useful context for a valuation discussion.