This appreciation calculator estimates an asset’s future value using its starting value, a fixed appreciation rate, and a holding period. Use it to explore potential growth in a home, investment, or collectible. The result is a projection based on your assumptions—not a market valuation or guaranteed return.
How to use the appreciation calculator
- Starting value: Enter the asset’s value at the beginning of your projection. Use its current value to estimate future growth, or its purchase price to model growth since purchase.
- Appreciation rate: Enter the percentage increase expected during each selected appreciation rate period. Enter 5 for 5%, not 0.05.
- Period: Set the total length of time over which the asset will appreciate.
- Appreciation rate period: Choose monthly, quarterly, or annually to match the rate you entered.
- Future value: Read the estimated asset value at the end of the projection.
The rate applies to each selected period. If you expect 5% growth per year, enter 5 and select annually. Selecting monthly instead applies 5% growth every month; it does not divide an annual 5% rate by 12.
For a constant monthly rate equivalent to 5% annual growth, use approximately 0.4074% monthly. Keeping an annual assumption paired with annually is usually the simplest way to avoid a rate mismatch.
What is appreciation?
Appreciation is an increase in an asset’s value over time. A home purchased for $300,000 and later valued at $330,000 has appreciated by $30,000, or 10% in total.
Appreciation is different from income. Rent, dividends, and interest payments are separate from changes in an asset’s price. An increase in value is generally an unrealized gain while you still own the asset; selling it turns that price change into a realized gain or loss, before considering costs and applicable taxes.
Appreciation formula and calculation method
The calculator applies compound growth: each period’s percentage increase is applied to the value reached at the end of the previous period. This follows the same mathematical principles of compound interest.
Future value = a × (1 + r/100)m ÷ (12/c)
- a: Starting value.
- r: Appreciation rate, entered as a percentage for each selected rate period.
- m: Total duration expressed in months, corresponding to the Period input—not an additional field.
- c: Number of appreciation periods per year: 12 for monthly, 4 for quarterly, or 1 for annually.
The exponent counts the appreciation periods. For example, three years contains 36 monthly periods, 12 quarterly periods, or three annual periods. In the standard compound-growth formula below, the rate is expressed as a decimal and the exponent is the number of matching growth periods.
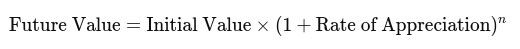
The formula does not divide the entered rate by the number of periods per year. Changing the rate period while leaving the rate unchanged changes the growth assumption.
Worked example: $2,000 growing at 5% annually
Enter a starting value of $2,000, an appreciation rate of 5%, a period of three years, and select annually. For annual appreciation, the number of growth periods equals the number of years:
Convert 5% to 0.05 and substitute the values:
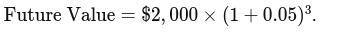
Future value = $2,000 × 1.053 = $2,315.25
| Year | Starting value | Appreciation during year | Ending value |
|---|---|---|---|
| 1 | $2,000.00 | $100.00 | $2,100.00 |
| 2 | $2,100.00 | $105.00 | $2,205.00 |
| 3 | $2,205.00 | $110.25 | $2,315.25 |
The annual dollar increase grows because the same 5% rate applies to an increasing value. Simply adding 5% of the original value each year would give $2,300 and would not match this calculator’s compound-growth method.
How to interpret your result
Future value is the projected total value, not the amount gained. You can calculate the implied appreciation from the result:
- Dollar appreciation = Future value − Starting value. In the example: $2,315.25 − $2,000 = $315.25.
- Total appreciation percentage = (Future value ÷ Starting value − 1) × 100. In the example: approximately 15.76% over three years, not 15.76% per year.
These are additional calculations you can make from the displayed future value. A higher projection reflects a higher assumed growth rate, a longer holding period, a larger starting value, or a combination of these—not necessarily a better investment.
Keep these limitations in mind:
- Growth is assumed to be constant. Actual asset values fluctuate and can fall. The calculator does not forecast market conditions.
- Values are nominal. The result does not adjust for inflation, so purchasing-power growth may be lower than the dollar increase.
- Appreciation is not net profit. The formula does not include financing costs, maintenance, fees, taxes, or income received from the asset.
- Projected price is not fundamental value. Assessing an investment’s intrinsic value requires more than extending an assumed growth rate.
Using the calculator for home and asset appreciation
Estimate a home’s future value
To use this as a home appreciation calculator, enter the property’s current estimated market value and a growth assumption supported by relevant local information. For example, a $300,000 home appreciating at 3% annually for 10 years would have a projected value of:
$300,000 × 1.0310 = $403,174.91
The implied increase is $103,174.91. This is property value appreciation, not home equity: calculating equity also requires subtracting the remaining mortgage balance. Estimating sale proceeds would require accounting for selling costs and other applicable expenses.
Compare assumptions before making a decision
Run separate lower, middle, and higher growth scenarios rather than relying on one estimate. Keep the starting value and holding period unchanged so you can see how sensitive the result is to the appreciation rate. These scenarios are planning assumptions, not probabilities.
For stocks or collectibles, use the same approach to model price growth. Keep dividends, storage, insurance, transaction costs, and other cash flows separate. If improvements add value to a property, assess their cost and expected contribution separately rather than assuming the fixed growth rate captures them.
Related calculators for evaluating asset growth
- CAGR Calculator: Calculate the compound annual growth rate from a known starting value, ending value, and holding period.
- Inflation Calculator: Explore how inflation affects the purchasing power of a projected asset value.
- Holding Period Return Calculator: Evaluate stock returns that include both price changes and dividends.
Build an asset-growth calculator for your website
Financial advisers and educational websites can use Calcopolis to build a customized growth calculator that helps visitors compare assumptions before requesting a consultation. Tailoring the inputs and explanations to your audience can make those conversations more informed.