The Graham Number Calculator estimates a stock’s valuation benchmark using earnings per share and book value per share. Compare the result with the current share price to identify stocks that may warrant closer research—not to establish a guaranteed fair value or a buy signal.
Associated with Benjamin Graham’s defensive approach to investing, the Graham Number combines profitability and accounting net assets in one calculation. It is one way to estimate intrinsic value, but it does not account for every factor that makes a business valuable or risky.
How to use the Graham Number Calculator
- Enter Book Value Per Share. Use the company’s common shareholders’ equity divided by common shares outstanding. Enter the per-share figure, not total equity or market capitalization.
- Enter Earnings Per Share. Use annual earnings per share, such as the latest fiscal-year or trailing-12-month EPS. Do not enter a single quarter’s earnings as though they represent a full year.
- Read the calculated Graham Number. The result is a price per share, displayed in dollars. Compare it separately with the stock’s market price; the calculator does not have a market-price input.
Use figures for the same company and share class, expressed in the same currency and on a consistent stock-split basis. Diluted EPS can help account for potential dilution, but be consistent when comparing companies or updating your analysis.
You can usually find these figures in company financial reports or financial-data services. Check whether the reported EPS is basic, diluted, or adjusted, because that choice affects the result.
The Graham Number formula
Graham Number = √(22.5 × Book Value Per Share × Earnings Per Share)
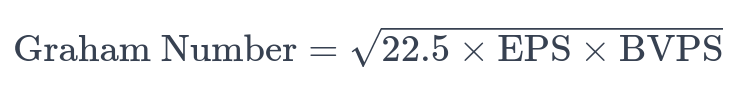
- Book value per share (BVPS) represents accounting equity attributable to each common share. It is not necessarily the amount shareholders would receive in liquidation.
- Earnings per share (EPS) represents earnings attributable to each common share over the selected annual period.
- 22.5 comes from multiplying a price-to-earnings benchmark of 15 by a price-to-book benchmark of 1.5.
The calculator multiplies the two inputs by 22.5 and takes the square root. Because both inputs are dollar amounts per share, the result is also a dollar amount per share.
Why does the formula use 22.5?
For positive EPS and book value, the relationship between market price and the two valuation ratios is:
P/E × P/B = Share Price2 ÷ (EPS × BVPS)
Setting that product equal to 22.5 and solving for share price gives:
This is a combined valuation test. A price below the Graham Number does not necessarily mean that P/E is below 15 and P/B is below 1.5 individually; one ratio can exceed its benchmark if the other is sufficiently low.
This is not Graham’s separate growth-based valuation formula. Calculators described as a “Benjamin Graham formula calculator” may use expected earnings growth and, in some versions, a bond-yield adjustment. This calculator uses only EPS and book value per share.
Worked example: calculating and interpreting the result
Suppose a company reports the following:
| Input | Value |
|---|---|
| Book value per share | $40.00 |
| Annual earnings per share | $4.00 |
Graham Number = √(22.5 × $40 × $4) = √3,600 = $60 per share
If the stock trades at $48, it is $12 below the calculated benchmark. That is a 20% discount to the Graham Number:
Discount = ($60 − $48) ÷ $60 × 100 = 20%
Do not confuse this discount with potential price appreciation. A rise from $48 to $60 would be 25%, because that calculation uses the purchase price as its denominator. Neither percentage predicts that the stock will reach $60.
What does a stock’s Graham Number tell you?
- Market price below the result: The stock trades below the earnings-and-book-value benchmark. Investigate whether the apparent discount reflects an opportunity or deteriorating business conditions.
- Market price near the result: The price roughly matches this formula’s benchmark, but the underlying earnings and assets still need scrutiny.
- Market price above the result: The stock exceeds this benchmark. The premium may reflect expected growth, valuable intangible assets, or overoptimistic expectations; the formula cannot distinguish among them.
A higher Graham Number is not automatically better. Per-share amounts depend partly on the number of shares outstanding, so use the result relative to the same stock’s price rather than ranking companies by their Graham Numbers alone.
Using a margin of safety
If you choose to require a discount to the estimate, calculate a separate screening price:
Screening price = Graham Number × (1 − Required discount)
For the $60 example, a personally selected 25% discount gives a screening price of $45. That percentage is an assumption, not a universal recommendation, and a discount to an inaccurate valuation does not guarantee protection from losses.
When the Graham Number can be misleading
- Negative or zero inputs: Use positive EPS and positive book value for a meaningful valuation screen. One negative input makes the square root non-real. Two negative inputs can produce a positive mathematical result, but it is not a valid valuation under this approach. A zero input produces zero, not proof that a business is worthless.
- Unusual earnings: Asset sales, tax benefits, restructuring charges, or a cyclical earnings peak can distort EPS. Small positive earnings are mathematically valid, but may produce a poor benchmark if they are unrepresentative.
- Accounting value versus economic value: Book value reflects accounting rules and may differ substantially from the current value of assets. Standard book value can include goodwill and other intangible assets; this calculator does not automatically substitute tangible book value.
- Growth and asset-light businesses: The formula does not explicitly value future growth, brands, software, or intellectual property. A low book value can make it less informative for businesses whose value depends heavily on those assets.
- Financial risk: Positive earnings and equity do not establish strong cash flow, manageable debt payments, or dividend sustainability. A low price relative to the result can still describe a financially troubled company.
Turn the result into an investment research checklist
- Check earnings quality. Review several years of results and compare reported profits with operating cash flow. Recalculate after new financial reports or material changes to earnings or equity.
- Examine leverage and profitability. Use the debt-to-equity ratio to investigate financing risk, and review return on equity alongside return on assets. High ROE can partly reflect leverage rather than superior operating performance.
- Test another valuation perspective. Compare the result with peer valuations or a cash-flow-based estimate. A large disagreement is a reason to investigate assumptions, not simply select the most favorable number.
- Separate valuation from investment performance. Your cost basis records what you paid; it does not determine current fair value. After investing, holding period return measures your actual gain or loss, including distributions.
Related valuation calculators
These tools help explain the Graham Number’s components or provide another valuation perspective:
- P/E Ratio Calculator: Compare market price with annual EPS to see the earnings multiple investors are paying.
- Price to Book Ratio Calculator: Compare market price with accounting equity per share.
- Intrinsic Value Calculator: Explore a separate growth-oriented valuation estimate and compare its assumptions with the Graham Number.
For broader analysis, an EBITDA multiple compares enterprise value with EBITDA rather than measuring investment return. Present value of growth opportunities examines the portion of value attributed to future growth, while CAPM estimates a required return based on systematic risk—not a stock’s fair price.
Build a valuation calculator for your website
An investor-education website could offer a custom tool that combines EPS and book value with a visitor’s chosen market price and discount target. Use Calcopolis’s AI calculator builder to create a customized valuation calculator that makes those assumptions clear and returns a useful screening estimate.