The Future Value of Annuity Calculator estimates how much a series of equal recurring payments could accumulate to over a specified term. It compares payments made at the end of each period, called an ordinary annuity, with payments made at the beginning, called an annuity due.
Here, “annuity” means a regular payment stream. You can use the calculation for a savings plan without purchasing an insurance annuity. The result assumes a constant interest rate; it is a projection, not a guaranteed investment return.
How to use the future value of annuity calculator
- Choose the annuity type. The option labeled “Ordinal annuity” means ordinary annuity: payments occur at the end of each period. Choose annuity due for beginning-of-period payments.
- Enter the payment amount. This is the amount of each contribution, not your annual contribution total. For example, enter $100 if you contribute $100 each month.
- Enter the annual interest rate. Enter 5 for 5%. The formula treats this as a nominal annual rate divided by the selected compounding frequency, not as an effective annual yield or APY.
- Set the annuity term. Enter how long payments continue. The examples below use a term in years.
- Select compounding. Choose monthly, quarterly, or annually to indicate how often interest compounds.
- Select payment frequency. Choose monthly, quarterly, or annually to indicate how often you contribute. Review the frequency limitation below if this differs from compounding.
The ordinary-annuity result is labeled “Future value (ordinal),” while the beginning-of-period result is labeled “Future value (due).” Use the result that matches your actual contribution schedule.
Future value of annuity formula
When payments and compounding occur at the same frequency, the ordinary annuity future value formula is:
FVordinary = P × [(1 + r)n − 1] ÷ r
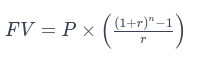
- P is the payment amount.
- r is the interest rate per payment period, expressed as a decimal.
- n is the total number of payments.
For monthly payments and monthly compounding, divide the nominal annual rate by 12 and multiply the number of years by 12. For quarterly schedules, use 4 instead.
Each payment earns interest for a different length of time. In an ordinary annuity, the final payment is made at the end of the term and earns no interest before the valuation date.
Future value of an annuity due
With an annuity due, each payment arrives one payment period earlier. When payment and compounding frequencies match:
FVdue = FVordinary × (1 + r)
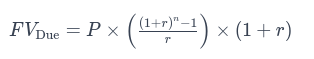
At a positive interest rate, beginning-of-period contributions produce a higher future value because every payment earns one additional period of interest. Both calculations include the same number of payments.
Example: $100 per month for 10 years
Suppose you contribute $100 monthly for 10 years at a nominal annual interest rate of 5%, compounded monthly.
- Monthly rate: 0.05 ÷ 12
- Number of payments: 10 × 12 = 120
- Total contributions: $100 × 120 = $12,000
For end-of-month payments:
FVordinary = $100 × [(1 + 0.05/12)120 − 1] ÷ (0.05/12) = $15,528.23
For beginning-of-month payments, multiply the unrounded ordinary-annuity result by 1 + 0.05/12.
| Payment timing | Total contributions | Projected interest | Future value |
|---|---|---|---|
| End of each month: ordinary annuity | $12,000.00 | $3,528.23 | $15,528.23 |
| Beginning of each month: annuity due | $12,000.00 | $3,592.93 | $15,592.93 |
Contributing at the beginning of the month adds approximately $64.70 over this term without increasing total contributions. Whether that schedule is practical depends on when your money becomes available.
Important calculation limits
Different payment and compounding frequencies
The calculator lets you select payment and compounding frequencies separately, but its implemented formulas are:
FVordinary = P × [(1 + j/c)cT − 1] ÷ (j/p)
FVdue = FVordinary × (1 + j/c)
Here, j is the annual interest rate divided by 100, c is compounding periods per year, p is payments per year, and T is the term in years.
These expressions match the standard annuity formulas when c = p. When the frequencies differ, they do not generally calculate the standard future value of the stated payment stream. In particular, the due formula adds one compounding period rather than one payment period.
For a standard rate-equivalent calculation with differing frequencies, first calculate the effective rate per payment period:
r = (1 + j/c)c/p − 1
Then use that rate in the standard annuity formulas with n = p × T, assuming a whole number of payments. This conversion is not used by the calculator’s supplied formulas. If your actual frequencies differ, verify the projection separately rather than changing an input merely to make the frequencies match.
Zero interest and partial periods
At 0% interest, future value equals total contributions: P × p × T, regardless of payment timing. The supplied formulas divide by the interest rate, so direct evaluation at zero is undefined.
For the clearest interpretation, use a term containing a whole number of payment periods. The formulas do not separately schedule partial payments or calculate interest by individual calendar dates.
How to interpret and apply your result
Future value includes both your contributions and projected interest. To see how much growth contributes to the result, subtract your total payments from the ending value, as shown in the example.
- Test a savings goal. For an education fund or another savings plan, compare the projected balance with your target. Adjust the payment amount or term to explore the gap.
- Compare affordable contribution levels. With all other inputs unchanged, increasing each payment by 20% increases the calculated future value by 20%.
- Test return assumptions. Run lower, middle, and higher rate scenarios. A constant rate does not model market volatility, and an investment’s historical compound annual growth rate does not guarantee future performance.
- Connect accumulation to retirement spending. A projected balance alone does not establish retirement readiness. Explore withdrawals with the Living Off Savings Calculator or broader early-retirement goals with the FIRE Calculator.
The result is a nominal dollar amount: it does not separately deduct inflation, taxes, or fees. It also excludes any starting balance because there is no initial-investment input. Review the projection alongside your assets and debts using the Net Worth Calculator.
This calculation cannot determine whether an insurance annuity is a suitable purchase. Contract guarantees, insurer risk, withdrawal restrictions, charges, and tax treatment require separate evaluation.
Related calculators
- Present Value of Annuity Calculator: discount future equal payments to determine their value today.
- Compound Interest Calculator: explore compound growth, particularly when you have an existing lump sum to invest.
- Inflation Calculator: assess how changing prices affect the purchasing power of a future balance.
Offer savings projections on your website
Financial planners and savings educators can use Calcopolis to build a custom savings calculator for WordPress. Let visitors explore contribution amounts and time horizons before discussing a plan with your team.